Saturday, August 17, 2013

Introducing Mint.com


United Financial Counselors
2205 Hollywood Blvd. Suite B Hollywood FL. 33020
www.UnitedCounselors.org Local: 786-288-5320 Toll Free: 877-509-3160
A Local Financial Counseling Organization Specializing In:
Mortgage Modifications, Money Management, Credit Restoration

Introducing: MINT.com!

Your financial life, all in one place


Mint aggregates all your accounts

Mint pulls all your financial accounts into one place. Set a budget, track your goals and do more

with your money, for free! Watch the short video
View your personal finances online

Makes your life easier

At Mint, we believe money is for living. So we make everything
simple and streamlined. Sign up takes less than five minutes.
Then Mint automatically pulls all your financial information into
one place, so you can finally get the entire picture.


Stay on top of your finances

Gives you total visibility

Stay on top of your finances. See what's happening with all your accounts – checking, savings, investments, retirement – at any moment of the day. And our free mobile apps mean you can track your money on-the-go.

Mint helps you set budgets and goalsHelps you reach your goals

Set a budget and create a plan to reach your personalfinancial goals. You can track your progress online or stay up-to-date with monthly emails. And we'll help you achieve your goals faster with helpful free advice and next steps.
Mint is always safe and secure

Trusted, safe and secure

Mint has more than 10 million users who know their information is
always secure. That's because we use 128-bit SSL encryption – the same
security that banks use – and all data is protected and validated by
VeriSign and TRUSTe. Plus, since Mint is read-only, no money can be
moved in or out of any account. Learn more
Mint is highly acclaimed

Over 10 million users agree


We've been a Money Top Pick, a PC Magazine Editor's
Choice, and we've won awards from Kiplinger's, The
Webby's, CNN Money and more. But we're most proud of
the raves from our 10 million users.
More awards and reviews | More testimonials

Saturday, July 27, 2013

Disputing Items on Your Credit Report!!

  Disputing Items on Your Credit Report

United Financial Counselors
A Not For Profit Organization
Local: 786-288-5320 Toll Free: 877-509-3160

It’s a good idea to monitor your credit report so that you can be aware of any out of the ordinary charges or comments. Here’s how to dispute anything that shouldn’t be there.
While the majority of the time, your credit report will be accurate, occasionally there are items that are reported incorrectly by your creditors. These might include:
  • Late payments
  • Amounts still owed
  • Accounts appearing open that should be closed
There are many reasons that a creditor might have incorrect data on your report. Data on the report may lag in what’s actually being done on your account, so if you recently closed an account, it may take a while for this to appear on your report. A payment may not have been processed by the due date, leaving a late payment mark on your report.
Most of these issues can be amended if you send a letter disputing the problem to the credit monitoring agency.

Why You Should Care

Your credit score affects many things, from getting a loan to your next job. It’s important to know what your score is and what the activity on your credit is to ensure it’s all accurate to your actions. It’s also a good way to ensure you’re not a victim of identity theft, and that someone isn’t using your cards and pretending to be you.

First Steps

If you recently made a change to your credit, wait up to 60 days to let your credit report reflect the change. Also, log into your credit accounts online to see if anything strange shows up that reflects the discrepancy that appears on your report. The more information you are armed with, the easier disputing it will be.

Next: Write a Letter

Craft a letter to the credit reporting agency you’re working with. There are three: Experian, Transunion andEquifax. The letter should list the charges or issues you’re concerned with, as well as any documented proof that this is incorrect. Request that this be removed.
Send your letter by certified mail, and get a return receipt so that you know when the letter has been received. Once the reporting agency gets the request, it will contact the creditor on your behalf to determine whether your request is valid. The agency must act within 30 days of your request by law, and once the investigation is complete, you will receive written notice. If it changes your credit report, you will be given a free copy of your report, which doesn’t go toward your annual free copy.
You may also choose to send notice to your creditor that you are disputing the item. This can be a good idea, so that the creditor has this on file.
In the event that the creditor says your dispute isn’t valid, you are able to submit a brief 100 word statement that will appear below the item on your credit report. This will appear to anyone who views your credit report. While it’s best to get the issue removed completely from the report, this is the next best thing.

Staying on Top of It

Take advantage of getting a free credit report from each of the three agencies each year, and take the time to review it in detail. Look to see who has viewed your credit report. It should only be people you’ve given access to your information, such as a credit card company you applied to open a card with, a landlord you granted permission to do a background and credit check, or a potential employer. Anyone else may be a red flag that you’re being looked at as a potential identity theft victim, so contact your reporting agency to find out more.


Tuesday, June 11, 2013

SPECIAL ALERT! FLORIDA’S NEW FORECLOSURE BILL HB 87 – HOMEOWNER’S AND CONDOMINIUM ASSOCIATION LIEN’S CAN NO LONGER BE FORECLOSED…


United Financial Counselors
A 501(c)3 Not For Profit Organization
www.UnitedCounselors.org


There are so many elements of this bill that will be picked apart, but let’s start with the fact that, according to the explicit definitions of this new law, a condominium or homeowner’s association cannot state a cause of action (or simply cannot foreclose).  

For all those lobbyists that didn’t bother to actually read this bill, let me draw your attention to line 90:

702.015 Elements of complaint;
2) A complaint that seeks to foreclose a mortgage or other lien on residential real property, including individual units of condominiums and cooperatives…MUST:
(a) Contain affirmative allegations expressly made by the plaintiff at the time the proceeding is commenced that the plaintiff is the holder of the original note secured by the  mortgage; or
(b) Allege with specificity the factual basis by which the plaintiff is a person entitled to enforce the note under s. 107 673.3011.

Now, experienced practitioners out there will recognize two things.  First, this new section of statute applies to “other liens” on property, not just mortgages….and condo/hoa liens are “other liens” and next…..
A CONDO OR HOA CANNOT COMPLY WITH EITHER OF THE A OR B “MUST” SECTIONS!

Meaning unless the debt is held by a note they CANNOT foreclose! Looks like the HOA attorneys are going to have a field day with this!


Sunday, June 9, 2013

Watch Out Florida Homeowners: Gov. Scott signs controversial fast-track foreclosure bill into law

United Financial Counselors

A 501(c)3 Not For Profit Organization
Local: 786.288.5320 Toll Free: 877-509-3106 - www.UnitedCounselors.org

Thursday, May 16, 2013

Thank You For Your Support!!!

United Financial Counselors
A 501(c)3 Not-For-Profit Organization
Toll Free: 877-509-3160      Local: 786-288-5320
 
 
By clicking the email you have automatically signed up to receive the United Financial Counselors outreach package! All clicks are tracked. If we have your address on file, your package will be sent by Wednesday May 22nd. If your address is not on file, we will request it within 48 hours!
 
 We hope that you will utilize the contents to help others in need of assistance.
 
We recommend you provide the contents of the package to members of your place of worship, social groups, facebook friends, your next door neighbor, and others that you run into everyday!
 
Thank you again for the opportunity to help you and your family!
 
The United Financial Counselors Team!


Sunday, April 21, 2013

Countrywide Borrowers Settlement - April 26th Deadline


Brought to you by:

United Financial Counselors
A Not For Profit Consumer Advocacy Group
For More Information on Mortgage Modifications, Short Sales & Bankruptcy Relief Visit:
Check Out The Highlighted Areas Below For Key Information

United States vs. Countrywide

HCE Cases black banner


Notification Begins to Borrowers Eligible for Payments from $335 Million Lending Discrimination Settlement Between the Department of Justice and Countrywide Financial Corporation (United States v. Countrywide Financial Corp., et al. (C.D. Cal., December 2011)

          Independent Settlement Administrator Rust Consulting, Inc. on November 16, 2012 began mailing letters to borrowers whom the United States has identified as entitled to payments from the Countrywide lending discrimination settlement fund. The letters notify recipients that they have been identified as victims, list the minimum payments they can receive, and include response forms.


          Borrowers receiving letters must sign and mail their response form by April 26, 2013 to participate in the settlement. The response form is designed to be easy to complete, and it can be returned using the prepaid envelope enclosed with the letter. In mid 2013, the Settlement Administrator plans to mail a letter with the exact payment amount and a release form to those who return the response form. Individuals with questions about the United States v. Countrywide Financial Corporation lending discrimination settlement may contact Rust, in English or Spanish, by telephone at 1-800-843-5148 or by email atinfo@CWFLSettlement.com.

          The $335 million settlement fund being administered by Rust was created as part of resolving the United States' allegations that Countrywide Financial Corporation and its subsidiaries engaged in a widespread pattern or practice of discrimination against more than 200,000 qualified Hispanic and African-American borrowers across the country who received mortgage loans from 2004 through 2008, as well as allegations of discrimination on the basis of marital status by encouraging non-applicant spouses to sign away their rights in jointly-held property when the applicant spouse took out a loan in his or her own name. Letters will go out at a later date to borrowers potentially affected by the alleged marital status discrimination.

          The settlement, which was approved by the U.S. District Court for the Central District of California, provided for an independent settlement administrator (Rust) to contact and distribute compensation payments at no cost to borrowers whom the department identifies as victims of Countrywide's discrimination. Rust's activities are overseen by the Department of Justice, and all of Rust's costs and expenses will be paid by Countrywide.

           A copy of the United States' lending discrimination complaint against Countrywide, the approved settlement order, and additional information about fair lending enforcement by the Department of Justice, can be found on the Department's website at www.justice.gov/fairhousing.

          The letters being mailed out beginning November 16 are the first mailing being sent to victims relating to the Countrywide lending discrimination settlement, although many Countrywide borrowers have previously received legitimate letters relating to other settlements with Countrywide not related to discrimination. Countrywide borrowers should treat with caution any mailings or phone calls that tell borrowers they must pay to participate in the settlement, or contacts that do not come from Rust related to the lending discrimination settlement, as such letters might be part of a scam. All mailings from Rust related to the lending discrimination settlement will have the seal of the United States Department of Justice and use the return address "Countrywide Fair Lending Settlement Administrator, c/o Rust Consulting, PO Box 8048, Faribault, MN 55021," and will ask victims to return response forms to that address. Any potential scams related to the Countrywide lending discrimination settlement should be reported to Rust by telephone at 1-800-843-5148, or to the Department of Justice at 202-514-4713.
          Today's announcement only addresses the Department of Justice's December 2011, $335 million settlement resolving claims that Countrywide discriminated in making loans. It is separate from the March 2012, $25 billion settlement between the Justice Department, the Department of Housing and Urban Development, 49 state attorneys general and the nation's five largest mortgage servicers to address mortgage loan servicing and foreclosure abuses. Individuals can obtain more information about that separate mortgage servicing settlement by visitingwww.nationalmortgagesettlement.com. Countrywide borrowers can contact Bank of America at 1-877-488-7814 to obtain information about loan modifications or other relief that they may qualify for under that separate settlement.

Sunday, April 7, 2013

SWEET JUSTICE!!!! YES!

United Financial Counselors

A Not For Profit Consumer Advocacy Group
www.UnitedCounselors.org

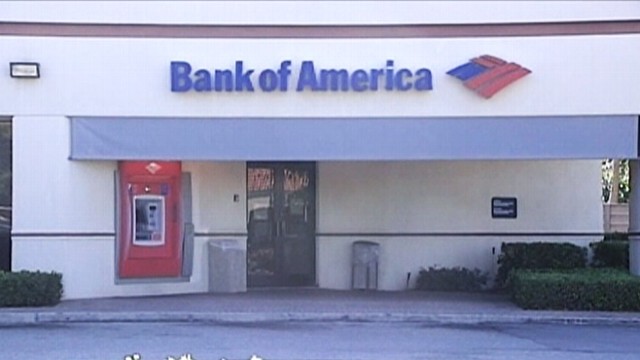
Homeowner Forecloses On Bank Of America

In Florida an angry homeowner whose home was wrongfully foreclosed on by Bank of America gets revenge by foreclosing on the bank's local branch. In Georgia, in a different property dispute, a city court judge threatens to jail the local BofA branch manager for contempt of court.

Any relation between the two incidents? "Just mere coincidences," says bank spokesperson Jumana Bauwens. Still, if you're BofA, you've got to be asking yourself: Where's the loveIn Florida an angry homeowner whose home was wrongfully foreclosed on by Bank of America gets revenge by foreclosing on the bank's local branch. In Georgia, in a different property dispute, a city court judge threatens to jail the local BofA branch manager for contempt of court.

Any relation between the two incidents? "Just mere coincidences," says bank spokesperson Jumana Bauwens. Still, if you're BofA, you've got to be asking yourself: Where's the love?
The Florida incident arose when the bank foreclosed on Warren and Maureen Nyerges of Golden Gate Estates in Naples. This surprised the Nyerges, since they had no mortgage--not with BofA or with anybody else. They had paid cash for their home in 2009.
Warren Nyerges made phone calls to the bank to try to get them to desist. "I talked to branch managers, I called anyone who would listen to me," hetold the Naples News. "I wrote a certified letter to the [bank] president. No response, nothing." Finally he hired an attorney. Two months later, the foreclosure had been dismissed.
Nyerges then sought to recover his attorney's fees, and got a judgment against the bank. Five more months passed: more phone calls, more letters; no payment. Nyerges went back to court and got a writ of execution, which gave him permission to seize bank assets in payment for his judgment.
VIDEO: A Florida family forecloses on Bank of America.
ABCNEWS.com
Video Story
Foreclosure Frustration Leads to Trashed Homes Watch Video
Man Takes His Home Hostage?!?Watch Video
On June 3, Nyerges, two sheriff's deputies and a moving truck showed up at the local BofA branch. The deputies informed the manager that he could either pay the Nyerges' legal fees— $2,500—or the movers would start taking away the bank's furniture and cash. The manager, after conferring with his superiors, gave the deputies a check.
Bank of America later apologized to the Nyerges in writing--but managed to misspell their name.
Their attorney, Todd Allen of Conrad Willkomm, P.A., remains disgruntled: "Bank of America never apologized for having tried to foreclose, only for not paying the money in time."
As to how the situation arose in the first place, Allen says the home's prior owner had defaulted, and that BofA had taken back the house. "My clients purchased the property directly from Bank of America. If they [the bank] had taken 15 minutes to review their records on the property, they would have seen the details of the transaction." In his view the Nyerges' story is "symptomatic of a larger problem: banks just aren't doing their due diligence before they start foreclosings."
His clients, he says, are "ecstatic--but drained emotionally. It's scary to have your home foreclosed on when you've paid cash for it."
Bauwens of Bank of America acknowledges a mistake was made: "Basically, we're truly sorry for the series of unfortunate circumstances that Mr. Nyerges experienced. He received a judgment—and rightly so. On Friday, that judgment was paid."
Still, she says of the incident, "It's not good for business."
Okay, then; on to Riverdale, Georgia, where a Bank of America branch manager is facing jail for contempt of court. "We are in conversations with the City of Riverdale to resolve this matter," says Bauwens, "and hope to do so."
In dispute here is who owns an abandoned home that has become, in the words of Dr. Evelyn Wynn Dixon, Riverdale's mayor, not just an eyesore but a safety hazard. "It needs to be demolished," she says. "It should have been torn down two years ago."